Empower Mothers: Achieve a Debt-Free Life
Personal Finance, Debt-Free Living, Women, Mothers, Immigrant Families
Dear Mothers: You Deserve a Debt‑Free Life
This is a loving wake‑up call to women and mothers—especially my fellow immigrant sisters—who are tired of living with debt hanging over their heads and are ready to build a peaceful, debt‑free, financially free life for themselves and their children.
To Every Woman, Every Mother, Every Potential Mother: This Is For You
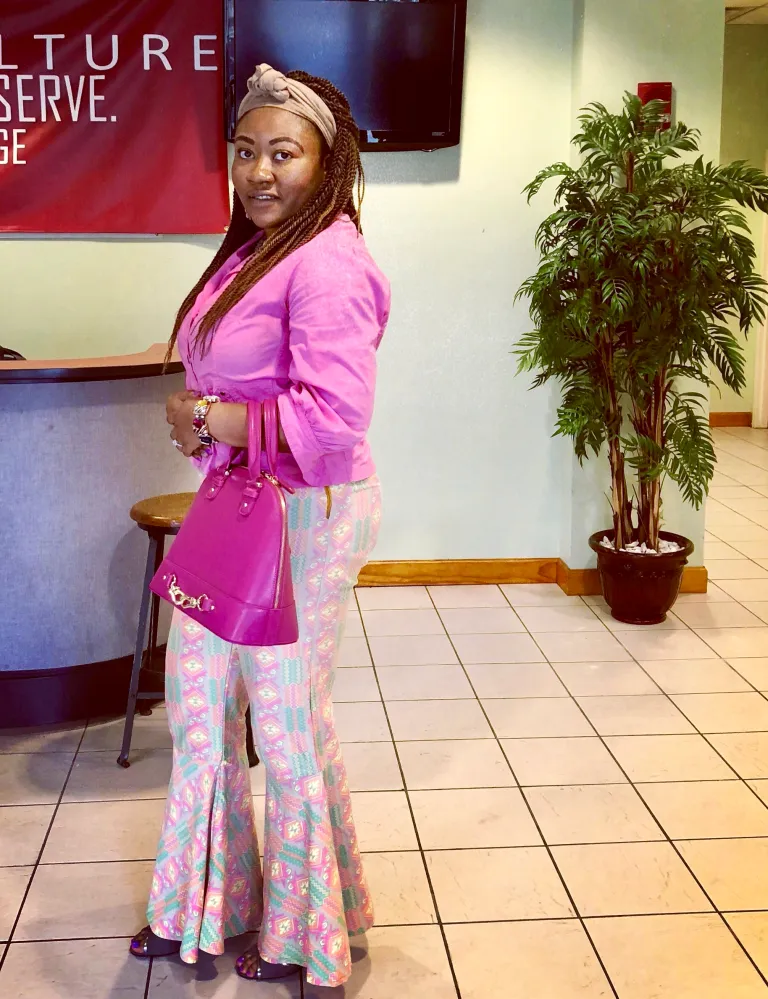
Mothers, women, and every woman who dreams of becoming a mother one day—this message is for you. I am writing to you not just as a professional who has spent 11 years in the financial services industry, and not just as someone with a master’s degree in social work, but as a wife, a mother, an immigrant woman, and a homeowner who has seen both sides of money: the stress of debt and the hope of financial freedom.
In this country, debt is treated like it’s normal. Credit cards maxed out? “Normal.” Car notes for years? “Normal.” A mortgage that feels like it will follow you to the grave? Also “normal.” But I want to gently challenge that today. Just because something is common does not mean it is healthy. Debt may be the norm, but financial freedom should be the standard we aim for .
The Conversation That Changed How I See Retirement
Recently, while I was on maternity leave, I reconnected with a former colleague who had just retired. As we talked, I asked her the question many of us wonder about: “So what’s next for you now that you’re retired?” Her answer shook me—in the best way possible.
She told me that she and her husband retired together, and that the home they owned in Bristol, Virginia, had built so much equity in just eight years that they were able to use it to pay cash for another home in Stafford, Virginia. No mortgage. No monthly payment hanging over their heads. And now, they are planning to move to Texas—with the intention of paying cash for another home there too.
I want you to pause and really picture that: retiring with your spouse, owning your home outright, and being able to buy another home with cash. No bank breathing down your neck. No thirty‑year mortgage. Just peace. Just options. Just freedom.
For me, as an immigrant woman and a mother, this story hit close to home. In the community I come from, you hardly hear stories like this. When someone wants a car, there is a car note. When someone wants a house, there is a mortgage. Almost everything is purchased on credit—and we are told that is simply how life is. But that conversation with my colleague reminded me: it doesn’t have to be that way.
My Own Homeownership Journey: A New Way of Seeing What’s Possible
I am also a homeowner. My family bought our first home in 2021. During that process, I learned something that honestly surprised me: people do purchase homes with all cash. No mortgage. No thirty‑year loan. At the time, it felt like this distant, impressive thing that other people did—people with “old money” or people who were “lucky.”
But hearing my former colleague’s story made it real. This was not a stranger on the internet. This was someone I knew, someone I had worked with. She had owned her home for eight years, built equity, and now that equity is helping her and her husband retire with dignity and peace—debt‑free.
I have owned my home for four and a half years. In just a few months, it will be five. When I think about her story, it gives me hope. It makes me say to myself: “One day, that could be me too—buying a retirement home in cash, using the equity I’ve built, or the business I’ve grown, and not being weighed down by a mortgage.” And if it can be me, it can be you too.
💡 Key Truth: Debt‑free living is not just for “other people.” With intention, patience, and wise choices, it is possible for you, your household, and your children’s future.
Why Debt Feels So Normal—Especially in Immigrant and Working Communities
When I first started working in the community as a social worker, one pattern kept showing up over and over again: lack of financial management, no emergency savings, and heavy debt. People were not “bad with money”—they were simply never taught how to manage it. Debt was treated as normal. It was just “how life works in America.”
Many of the individuals and families I met had so much debt that their credit scores were badly damaged. And in this country, whether we like it or not, credit is everything. It affects where you can live, what interest rates you pay, sometimes even the jobs you can qualify for. When debt is not managed, it doesn’t just sit quietly in the background—it actively works against your future.
In many immigrant communities, we arrive in this country with big dreams and strong work ethic. We work hard—sometimes two or three jobs. But we are not always given the tools to protect what we earn. We learn how to survive, but not always how to build. We learn how to pay bills, but not always how to create wealth. And that is where I want to see change—especially for women and mothers.
Needs vs. Wants: The Quiet Difference That Can Keep You in Debt—or Set You Free
Let’s start with something simple but powerful: knowing the difference between a need and a want. This is one of the most important skills you can teach yourself—and your children—if you want to live debt‑free.
Needs are things you must have to live and function: shelter, basic food, utilities, transportation to work, essential clothing, healthcare, childcare.
Wants are things that are nice to have but not necessary: the latest phone, another pair of shoes when you already have enough, eating out several times a week, impulse shopping because there’s a “sale.”
Ask yourself honestly: “Am I buying my needs, or am I buying my wants?” That simple question can save you from so much unnecessary debt. Because sales and discounts can be traps. You see “50% off” and feel like you’re saving money, but if you didn’t need that item in the first place, you are not saving—you are spending. And often, you are borrowing to spend, by using credit cards or buy‑now‑pay‑later options that quietly build up your debt.
💡 Pro Tip: Before every purchase, pause and ask, “Is this a need or a want? If I don’t buy this today, will my life or my children’s well‑being suffer?” If the answer is no, it’s likely a want.
As mothers, we often feel guilty when we say “no”—even to ourselves. We want to give our children a beautiful life, and sometimes we confuse that with giving them things. But a truly beautiful life is not built on toys, gadgets, and outfits. It is built on stability, peace, and health. A mother who is not constantly stressed about debt is a gift to her children.
“Cut Your Coat According to Your Size”: Living Within Your Real Capacity
Growing up, I often heard the saying, “Cut your coat according to your size.” It sounded simple, but it carries deep financial wisdom. It means: live within your means. Do not make big purchases just to impress people. Do not stretch yourself so thin that one missed paycheck could break you.
Many people make this mistake: as soon as a new job or promotion comes with higher pay, they immediately upgrade everything—new car, bigger house, more expensive lifestyle. But they do not stop to ask: “Can I sustain this if something changes? What if I lose this job? What if I get sick? What if I need to take time off for a new baby?” The income grows, but so do the bills—and the debt. Instead of creating more freedom, the higher salary creates more pressure.
True financial wisdom is being able to say: “Just because I can afford the monthly payment does not mean this purchase is good for my future.” You want to be able to manage your life and your major purchases even if your income changes. That is how you protect your peace and move closer to a debt‑free life.
Building Equity: Turning Your Home Into a Tool for Freedom, Not Stress
Let’s talk about equity, because this is one of the quiet ways families build wealth and move toward debt‑free living—especially when it comes to housing. Equity is simply the part of your home that you truly own. As you pay down your mortgage and as your home’s value increases, your equity grows. That equity can later help you:
Sell and buy another home with a much smaller or no mortgage at all.
Downsize in retirement and live with lower expenses.
Create stability for your children by always having a secure place to live.
My colleague’s story is a perfect example: eight years of homeownership, and the equity they built allowed them to purchase another home in cash. That is the kind of long‑term strategy that can change the story of an entire family line. It doesn’t happen overnight, but it does happen when you are patient, consistent, and intentional with your money choices.
💡 Equity‑Building Mindset: Instead of asking “What is the biggest house I can qualify for?”, ask “What is a comfortable home that still allows me to save, invest, and live without constant stress?”
Credit Health: Why It Matters and How Debt Can Quietly Harm It
In my years in financial services, I have seen how unmanaged debt destroys credit health. Late payments, maxed‑out credit cards, ignoring bills because they feel overwhelming—all of these quietly pull down your credit score. And a low credit score makes almost everything more expensive: higher interest rates, bigger deposits, limited housing options, and sometimes missed opportunities altogether.
Taking care of your credit health doesn’t mean you must live in fear of credit. It means you use it wisely and intentionally. Here are some empowering steps you can start with:
Know your numbers. Check your credit report regularly so you understand where you stand and what needs attention.
Pay on time, every time. Even minimum payments made on time are better than missing payments altogether.
Use less than you’re allowed. If your credit card limit is $1,000, aim to keep your balance far below that, ideally under 30% of the limit.
Have a payoff plan. Don’t just pay the minimum forever. Make a simple plan to reduce your balances month by month.
💡 Gentle Reminder: If your credit is not where you want it to be, you are not a failure. You are not your credit score. You can start today to heal it—step by step.
Teaching Our Children Early: Planting Seeds of Financial Wisdom
I often say: it is never too early to start teaching your children about money. In another blog post, I talk about how mothers and parents can begin financial education when their kids are still young, so that by the time they become teenagers, the knowledge is already rooted in them. We cannot complain that “debt is the norm” and then send our children into adulthood with no tools to break that cycle.
You can start simple:
Talk about needs vs. wants when you go shopping together. Explain why you are choosing not to buy certain things.
Encourage them to save a portion of any money they receive instead of spending it all immediately.
Share age‑appropriate stories about how you are working toward debt‑free living and why it matters for your family.
Our children are watching us. They learn more from what we do than what we say. When they see you choosing wisely, saying “no” to unnecessary debt, and prioritizing peace over pressure, you are already building something powerful: new financial habits for the next generation.
Generational Wealth: Not Just Money, But Legacy, Health, and Peace
When I talk about generational wealth, I am not only talking about leaving millions of dollars in a bank account—although building financial assets is important. I am also talking about leaving your children:
Healthy financial habits instead of patterns of debt and scarcity.
Good credit instead of damaged credit they must spend years repairing.
Assets—like a paid‑off home, savings, or a business—rather than unpaid bills and financial burdens.
I want to see my community—especially my immigrant community—come to this country not just to work hard and die tired, but to work hard and live well. To live without constant sickness from stress. To live long enough and peacefully enough to enjoy their grandchildren. To pass on more than stories of struggle, but stories of breakthrough and wisdom.
📌 Key Takeaway: Every time you choose to pay down debt, save an emergency fund, or walk away from an unnecessary purchase, you are not just helping yourself—you are building a new financial story for your children and grandchildren.
Practical First Steps Toward a Debt‑Free Life (Starting Exactly Where You Are)
You might be reading this and thinking, “This all sounds beautiful, but my situation is messy. I already have debt. I already feel behind.” If that is you, please hear me: there is no shame in where you are starting from, and it is never too late to begin again .
Here are some gentle but powerful steps you can begin taking today:
Face your numbers. Write down all your debts, minimum payments, and interest rates. Clarity is the first step to freedom.
Separate needs from wants. Look at your monthly spending and circle the true needs. Everything else is a want that can be reduced or paused while you focus on freedom.
Build a small emergency cushion. Even $500–$1,000 in savings can stop you from reaching for a credit card every time life happens.
Choose one debt to attack first. Maybe it’s the smallest balance or the highest interest rate. Make extra payments there while paying minimums on the others, then move to the next one.
Protect your credit health. Set reminders for due dates. Automate payments where you can. Each on‑time payment is a step toward a stronger financial future.
Remember: you do not have to do everything at once. You are a mother, a woman carrying many responsibilities. But you can take one step this week, and another next week. Over time, those steps add up to a completely different life.
Let’s Empower Each Other: A New Normal for Women and Mothers
I want to see more women, more mothers—especially immigrant mothers—living debt‑free. I want to see us going on vacation without constantly thinking about the bills waiting at home. I want to see us buying cars and homes in cash, or paying off our mortgages early, not because we want to show off, but because we deeply value peace and freedom.
I want to see our immigrant communities come here, not just to work themselves into sickness, but to work wisely, to build, to rest, and to leave behind good legacies for their children. A legacy of strong credit, thoughtful spending, equity in homes, and the confidence that comes from knowing: “We are okay. We are not at the mercy of debt.”
💬 Encouragement: You are not alone in this journey. Many of us are learning, unlearning, and rebuilding. Let’s keep speaking openly about money, supporting each other’s progress, and celebrating every small win.
Your Debt‑Free Future: A Picture Worth Working Toward
Close your eyes for a moment and imagine this: You wake up in a home that is fully yours. No mortgage payment due at the end of the month. Your car is paid off. Your credit is healthy. You have savings in the bank. When your children ask for something, you don’t feel panic—you calmly decide whether it’s a need or a want. When you go on vacation, you are fully present, not mentally arguing with your credit card statement. When retirement comes, you are not afraid—you are prepared.
This is not a fantasy. It is a destination. And like any destination, you reach it one step, one decision, one sacrifice, and one wise choice at a time. Your journey may be longer or shorter than someone else’s, but that does not matter. What matters is that you are moving in the right direction—toward freedom, not deeper into bondage.
Mothers, women, sisters: you carry so much on your shoulders already. Debt does not have to be one more heavy load. You deserve a life where your mind is clearer, your body is healthier, and your spirit is lighter because money is no longer a constant source of fear. That is what a debt‑free life offers—not perfection, but peace.
A Final Word From My Heart to Yours
As someone who has walked beside families through my work in social services, and who has worked in financial services for over a decade, I have seen what debt can do. I have also seen what discipline, wisdom, and community support can do. And now, as a mother and homeowner myself, I carry an even deeper desire to see women and mothers step into financial freedom.
So today, I am urging you—lovingly but firmly—to start striving toward a debt‑free life. Question your spending. Protect your credit. Build equity wherever you can. Teach your children early. And most importantly, believe that you are worthy of a life where debt is not hovering over your head like a dark cloud.
Let’s empower each other. Let’s talk openly about money. Let’s celebrate the small wins: the credit card you paid off, the emergency fund you started, the purchase you walked away from because you chose your future over a moment of impulse. These are not small things. They are the building blocks of a new normal—for you, for your children, and for the generations that will come after you.
You deserve to live your best life—healthy, joyful, mentally at peace, and financially free. And I am cheering you on, every step of the way. See you in the next blog, where we will keep learning, growing, and building this debt‑free, abundant life together.